Lucky Cement (PSX: LUCK): Record Earnings, a Fresh Expansion Cycle and a Stock Still Near 7x P/E
Almeer Securities view – key takeaways
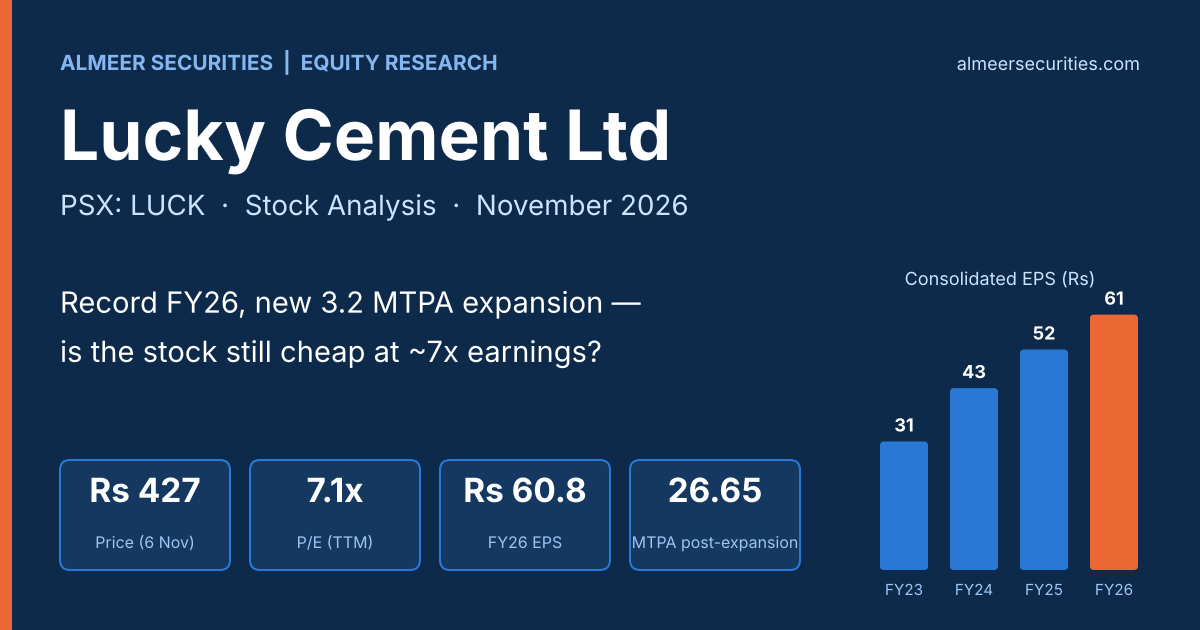
- FY26 was a record year: consolidated profit after tax of Rs96.5bn (+14%) and attributable EPS of Rs60.8 on revenue of Rs516bn.
- The core cement business is getting stronger: standalone gross margin reached 37.5% and standalone profit rose 17% YoY in 1QFY27.
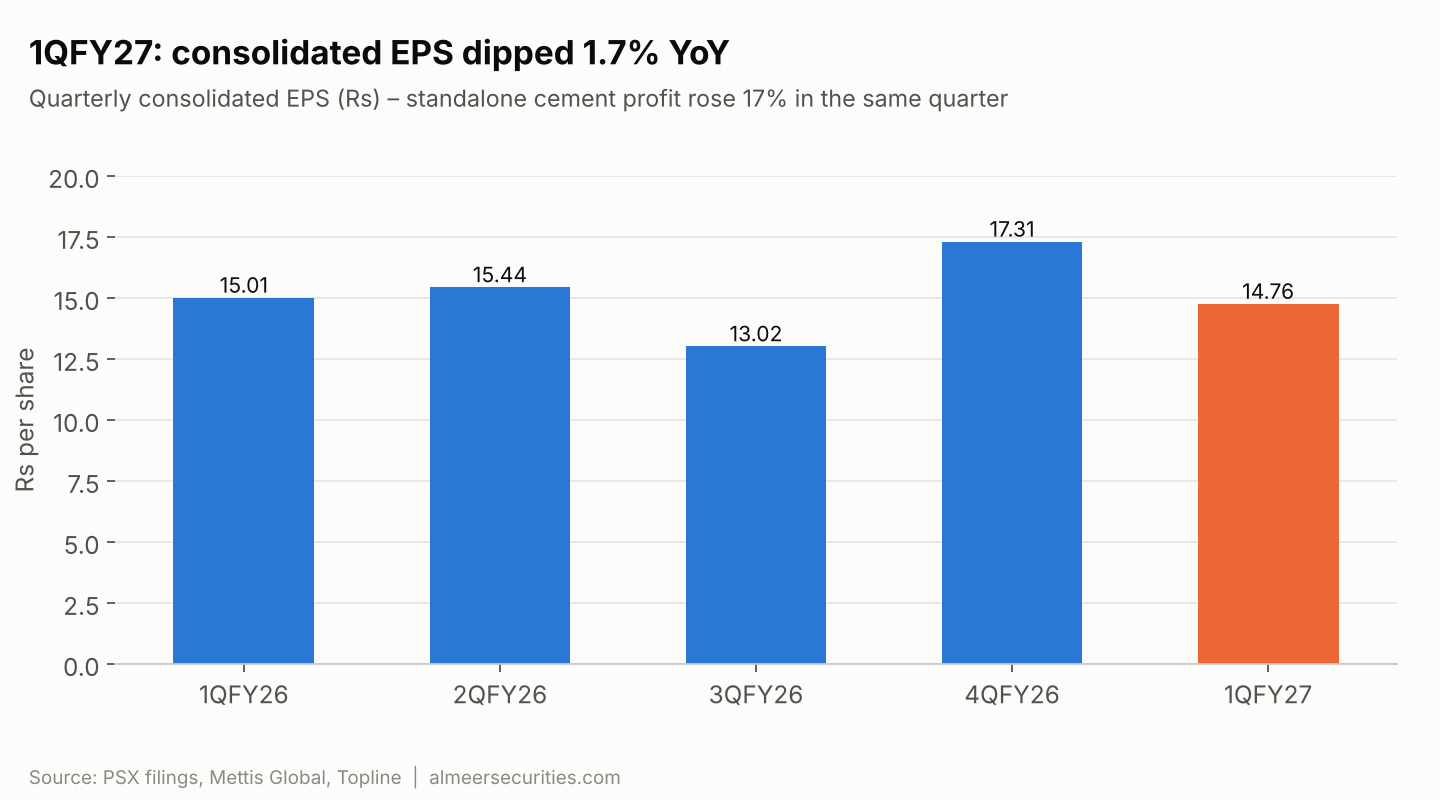
- Group profit softened in 1QFY27: consolidated EPS of Rs14.76 was 1.7% lower YoY, as subsidiaries and associates contributed less.
- Growth is back on the agenda: a 3.2 MTPA brownfield line at Karachi (target December 2027) and a 1.6 MTPA line in DR Congo.
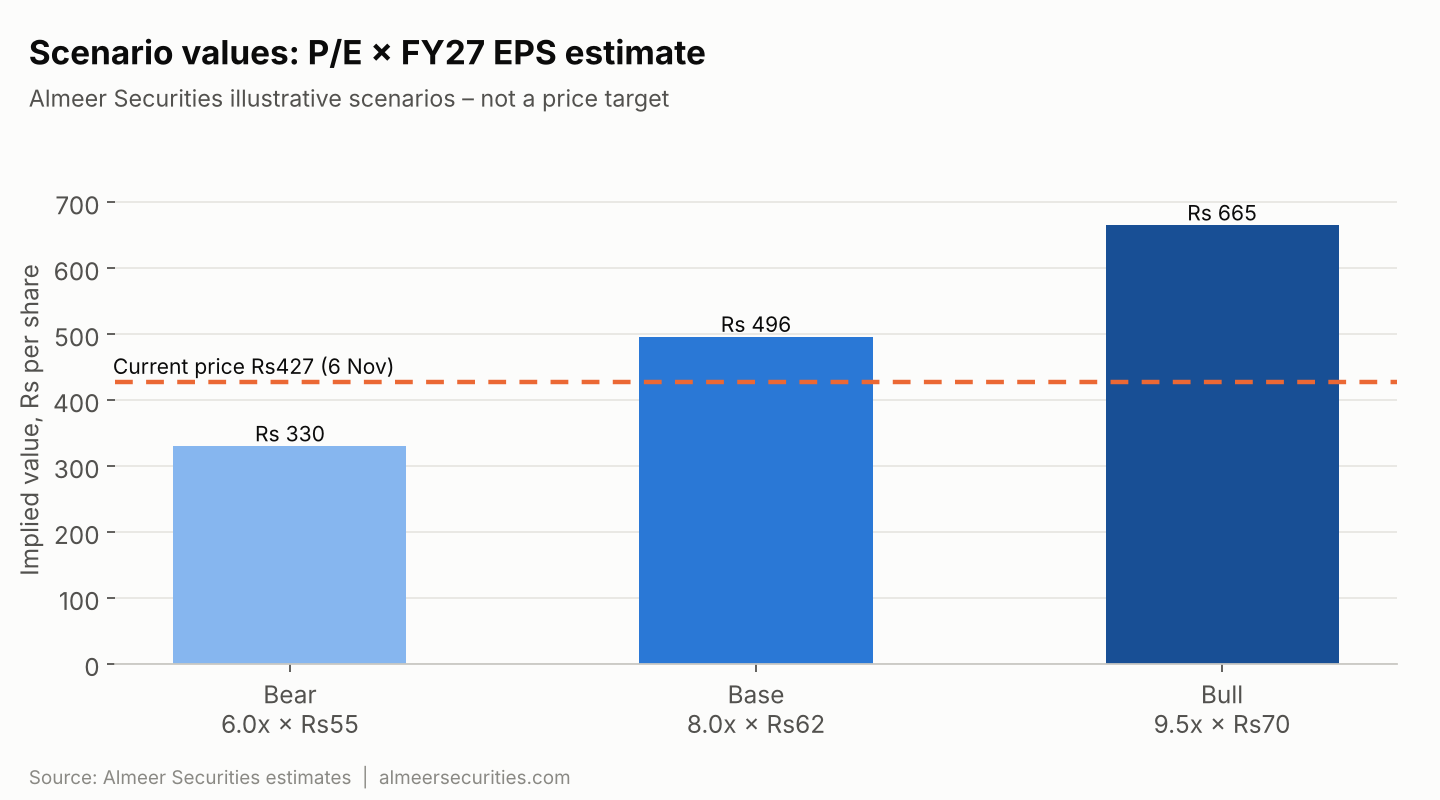
- Valuation looks undemanding: about 7x trailing earnings and 1.3x book. Our base-case scenario value is about Rs496 per share (+16%).
1. Company snapshot
Lucky Cement is Pakistan's largest cement producer and exporter, and it is also the holding company of a diversified group. Its businesses include Lucky Electric Power (coal-fired IPP), Lucky Motor Corporation (Kia, Peugeot and Samsung smartphones, with GAC now added), a 55% stake in Lucky Core Industries (chemicals, pharma, animal health) and cement operations in Iraq and the DR Congo. The company has 1,465 million shares of Rs2 face value after the 5-for-1 split. Free float is 30%.
The group structure matters for investors. Standalone (cement-only) profit was Rs46.6bn in FY26. Consolidated attributable profit was nearly double that, at about Rs89bn. When you buy LUCK, you are buying a cement leader and a Pakistani conglomerate together.
2. FY26: the best year in the company's history
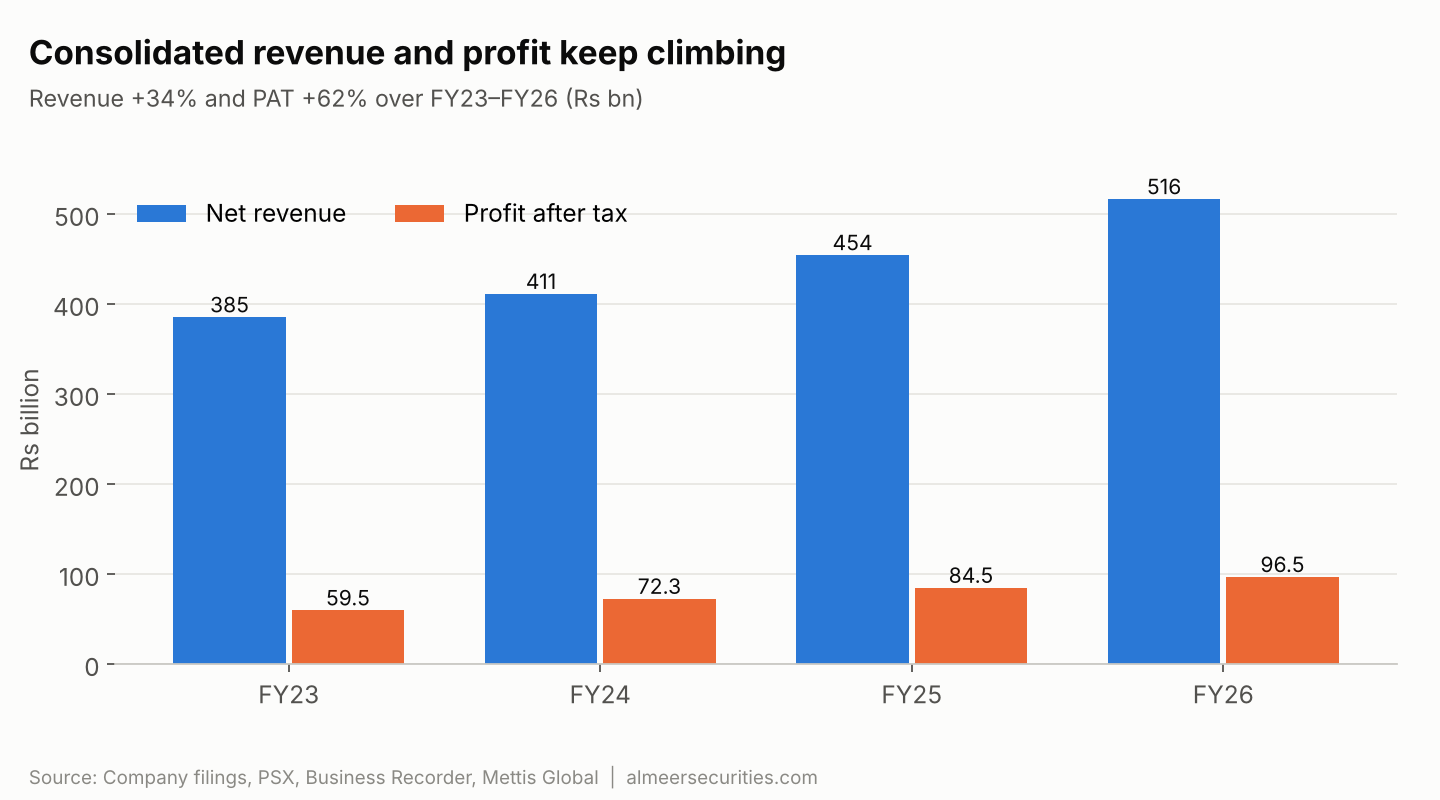
Consolidated net revenue grew 14% to Rs516.3bn in FY26. Growth came from local cement, Lucky Motors (auto volumes recovered sharply) and mobile phones. Consolidated profit after tax rose 14% to a record Rs96.46bn. Other income increased about 30% to Rs21bn, helped by a much larger cash pile. Consolidated cash and equivalents reached Rs181.9bn at June 2026, up from Rs141.7bn a year earlier. The board declared a final dividend of Rs5 per share, the highest in the company's history.
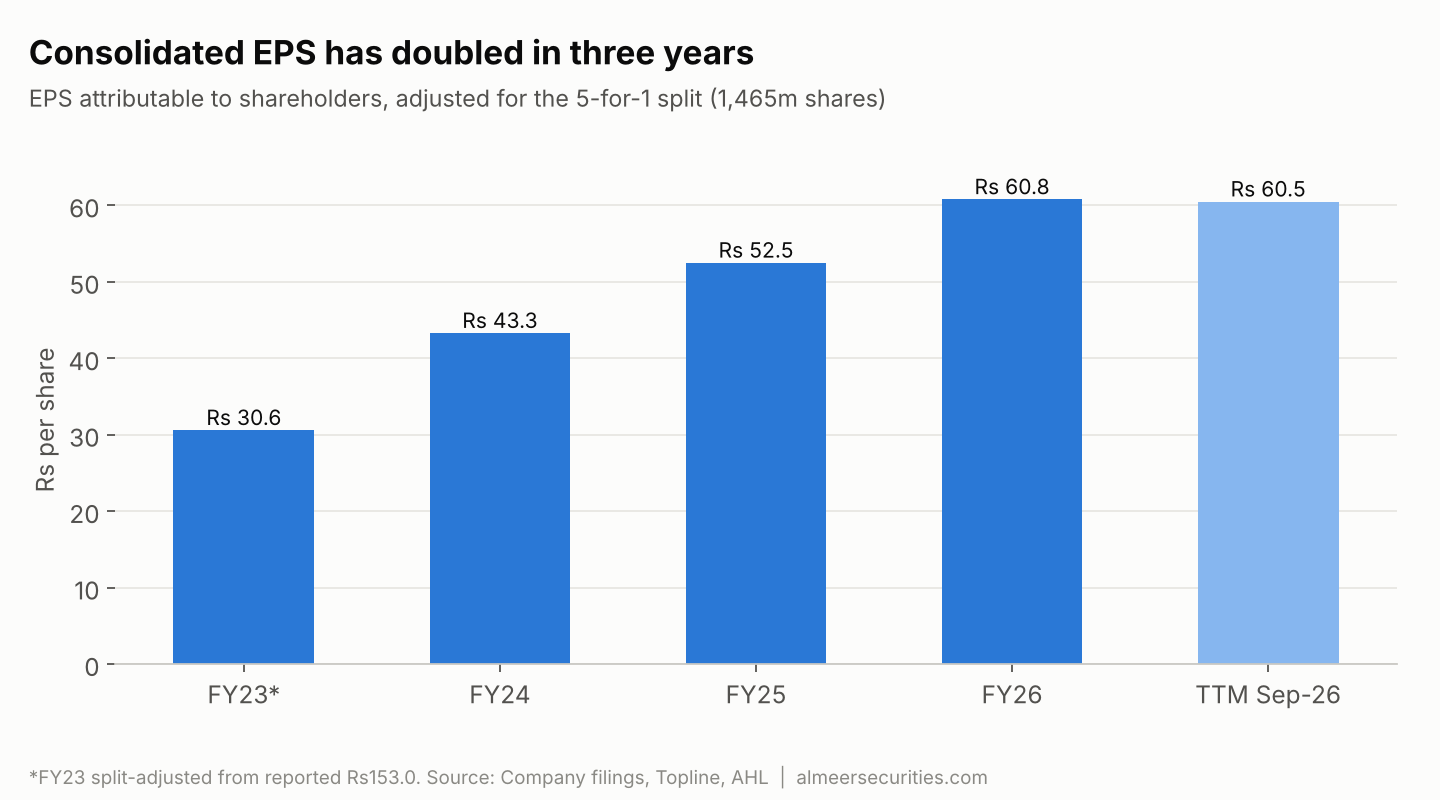
On a per-share basis, earnings have roughly doubled in three years. Attributable consolidated EPS (split-adjusted) went from about Rs31 in FY23 to Rs60.8 in FY26.
3. Cement core: volume share gains and higher margins
Pakistan's cement industry sold 50.5 million tonnes in FY26, up 7%. Lucky did better: its local volumes rose 10.1% to 6.5 million tonnes. The momentum continued into 1QFY27. Domestic sales rose 13% to 1.8 million tonnes and domestic market share increased to 16.8% from 16.1%.
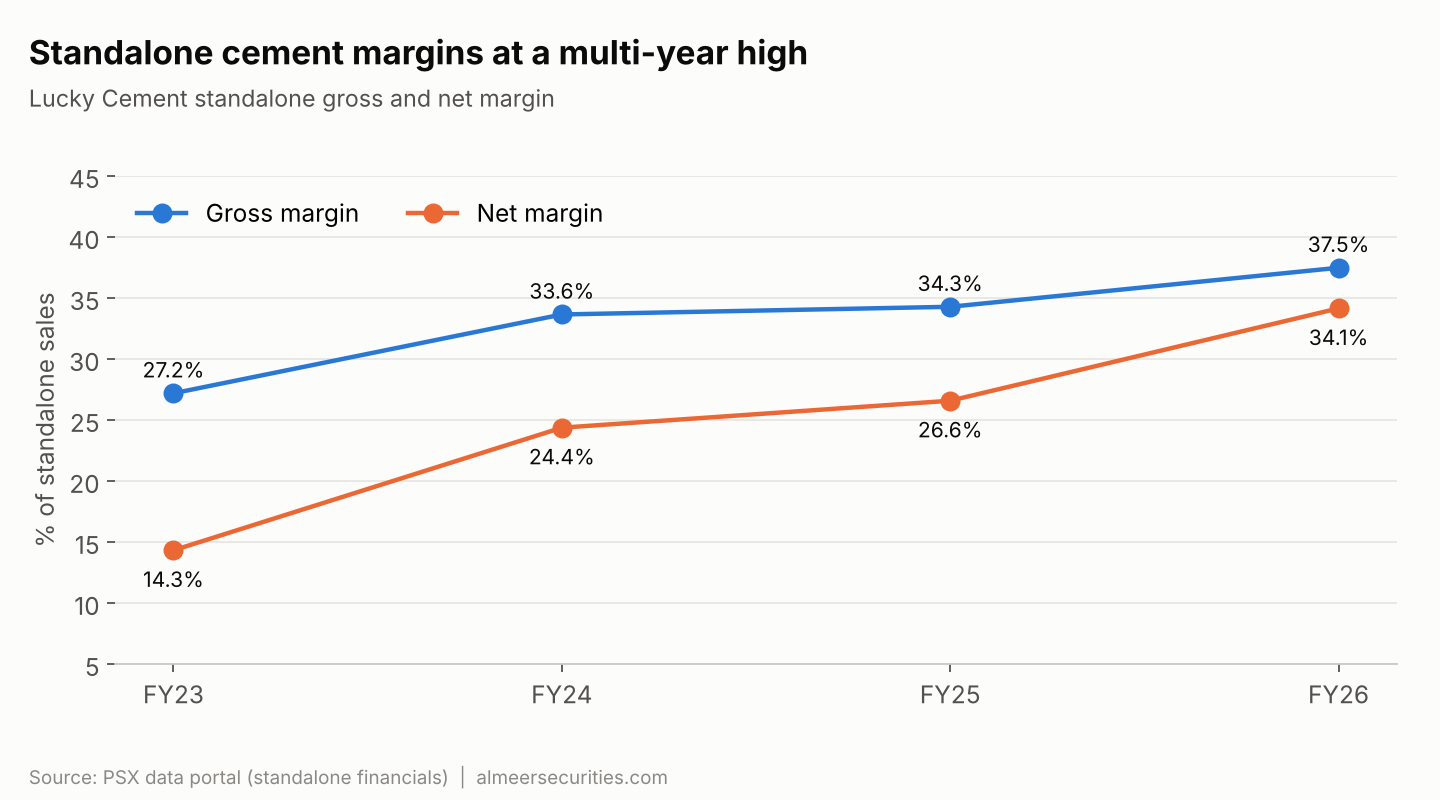
Profitability has improved at the same time. Standalone gross margin went from 27.2% in FY23 to 37.5% in FY26. Net margin went from 14.3% to 34.1%, helped by dividends from Lucky Electric (Rs12bn received in FY26). Three things drive the margin gains: renewable power (solar capacity is now 89.3 MW, and wind is being expanded), efficiency upgrades at the Karachi plant that reduce coal use, and management prioritising higher-margin domestic sales over exports.
4. 1QFY27 review: strong cement, softer group
| Rs bn (unless stated) | 1QFY27 | 1QFY26 | YoY |
|---|---|---|---|
| Standalone net revenue | 41.1 | 33.9 | +21% |
| Standalone gross profit | 15.1 | 13.2* | +14% |
| Standalone profit after tax | 17.1 | 14.6 | +17% |
| Standalone EPS (Rs) | 11.69 | 9.98 | +17% |
| Consolidated revenue | 131.9 | 123.6 | +5% |
| Consolidated profit after tax | 22.6 | 23.6 | –4% |
| Consolidated EPS (Rs) | 14.76 | 15.01 | –2% |
*Implied from reported growth. Sources: PSX filings, corporate briefing, ProPakistani, Mettis Global.
The cement business performed very well this quarter. Domestic dispatches grew double digits, and standalone profit was supported by dividend income from subsidiaries. At group level, profit fell slightly. Gross profit grew only 3% and operating profit was flat. Higher costs at subsidiaries and a smaller contribution from associates offset the gains in cement.
5. Expansion: the next leg of growth
The 1QFY27 briefing confirmed a new capex cycle. A 3.2 MTPA brownfield expansion at the Karachi plant is targeted to start commercial operations in December 2027. It will take Pakistan capacity to 18.8 MTPA and Karachi alone to 8.55 MTPA. Management expects the new line to cut average coal consumption from about 135 kg to about 125 kg per tonne of cement. In the DR Congo, the Nyumba Ya Akiba joint venture is adding a 1.6 MTPA integrated line, which more than doubles that plant to 2.91 MTPA. Construction is under way and completion is expected in about 18 months. The company is also adding 22.5 MW of wind at Karachi, plus solar and battery storage at Pezu. With all projects complete, management expects renewables to meet about 60% of cement energy needs.
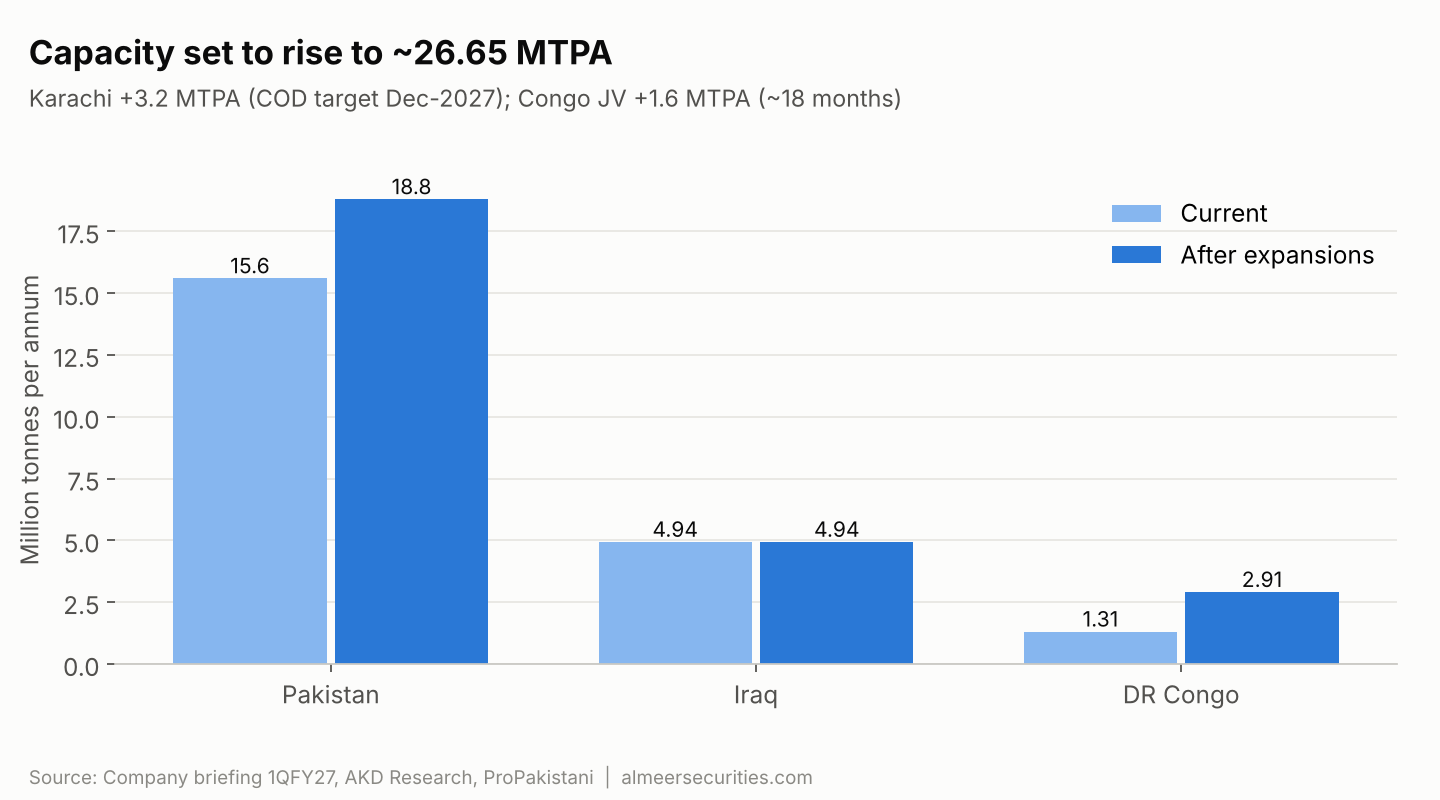
When all projects are complete, group cement capacity will be about 26.65 MTPA. The Karachi line is well located for exports from the south, where North-based mills cannot compete. North-based exports fell to zero in October 2026.
6. Industry backdrop
Domestic demand is growing but slowing down. Total industry dispatches for July–October 2026 rose 2.9% to 17.95 million tonnes. In October alone, domestic sales grew only 1.2% and exports fell 3.7%. Lower interest rates and stable inflation support construction activity. However, a new 3.2 MTPA line will enter a sector that already has surplus capacity. Lucky's cost advantage (renewables, scale, efficient kilns) is therefore what makes this expansion sensible.
7. Share price performance
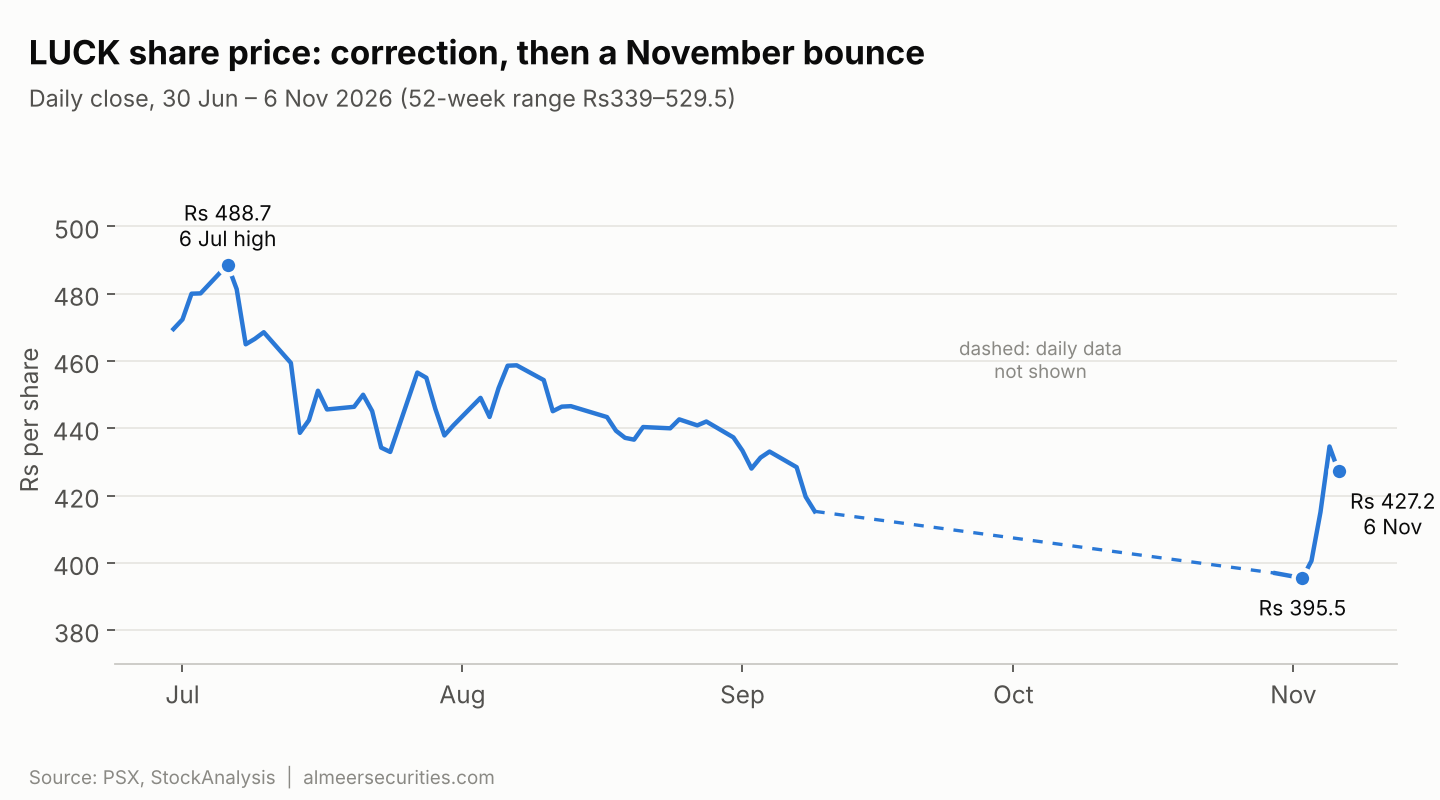
LUCK peaked near Rs489 in early July 2026. It then fell steadily through September and October, reaching about Rs396 at the end of October. This happened even though the company reported record annual results. The stock bounced in early November together with the broader KSE-100 rally and closed at Rs427.23 on 6 November.
8. Valuation
| Metric | Value |
|---|---|
| Price (6 Nov 2026) | Rs 427.23 |
| TTM consolidated EPS (Dec-25 to Sep-26) | Rs 60.53 |
| P/E – consolidated TTM | 7.1x |
| P/E – standalone TTM | 12.7x |
| Book value per share | ~Rs 323 |
| Price / book | ~1.3x |
| FY26 dividend / yield | Rs 5.0 / 1.2% |
| Consolidated cash per share (Jun-26) | ~Rs 124 |
We value LUCK using simple P/E scenarios on our FY27 consolidated EPS estimates. These are illustrative scenarios, not a formal target price. In the base case, EPS is about Rs62 (modest growth from FY26) and the multiple is 8x, close to the historical average. This gives about Rs496. In the bear case, EPS falls to Rs55 because of weaker auto and associate income and lower cement prices, and the multiple is 6x, giving about Rs330. In the bull case, EPS reaches Rs70 on stronger volumes and lower costs, and the multiple re-rates to 9.5x, giving about Rs665. For reference, published consensus targets average about Rs624 per share, so our base case is more conservative than the market.
9. Key risks
- Group earnings volatility: autos, power and associates can swing consolidated profit, as 1QFY27 showed.
- Overcapacity and pricing: new capacity across the industry could pressure retention prices if demand stays slow.
- Export weakness: industry exports are falling, and export margins are lower than domestic margins.
- Energy and coal costs: imported coal prices and the PKR exchange rate directly affect cement margins.
- International exposure: management has described near-term uncertainty in Iraq. The Congo expansion carries execution and country risk.
- Low payout: a Rs5 dividend (about 8% of consolidated EPS) means investors depend on capital gains, and on management using its cash well.
10. Almeer Securities conclusion
Lucky Cement combines Pakistan's most efficient large-scale cement franchise with a diversified, cash-generating group. The balance sheet holds more than Rs180bn in consolidated cash. The stock trades at about 7x trailing earnings, after a 13% fall from its July high. In our view, the market is focusing on a slightly weak group quarter and a slowing industry. It is giving too little credit for record margins, market-share gains and a clear expansion pipeline. We see LUCK as a core long-term holding in the cement sector, worth accumulating on dips. The main things to watch over the next 12 months are monthly dispatch data, coal prices, Lucky Motors' volumes and progress on the Karachi line.
Sources: PSX Data Portal; Lucky Cement financial results and 1QFY27 corporate briefing; APCMA; ProPakistani; Mettis Global; Business Recorder; CemNet; Global Cement; AKD Research; Topline Securities; AHL Research.